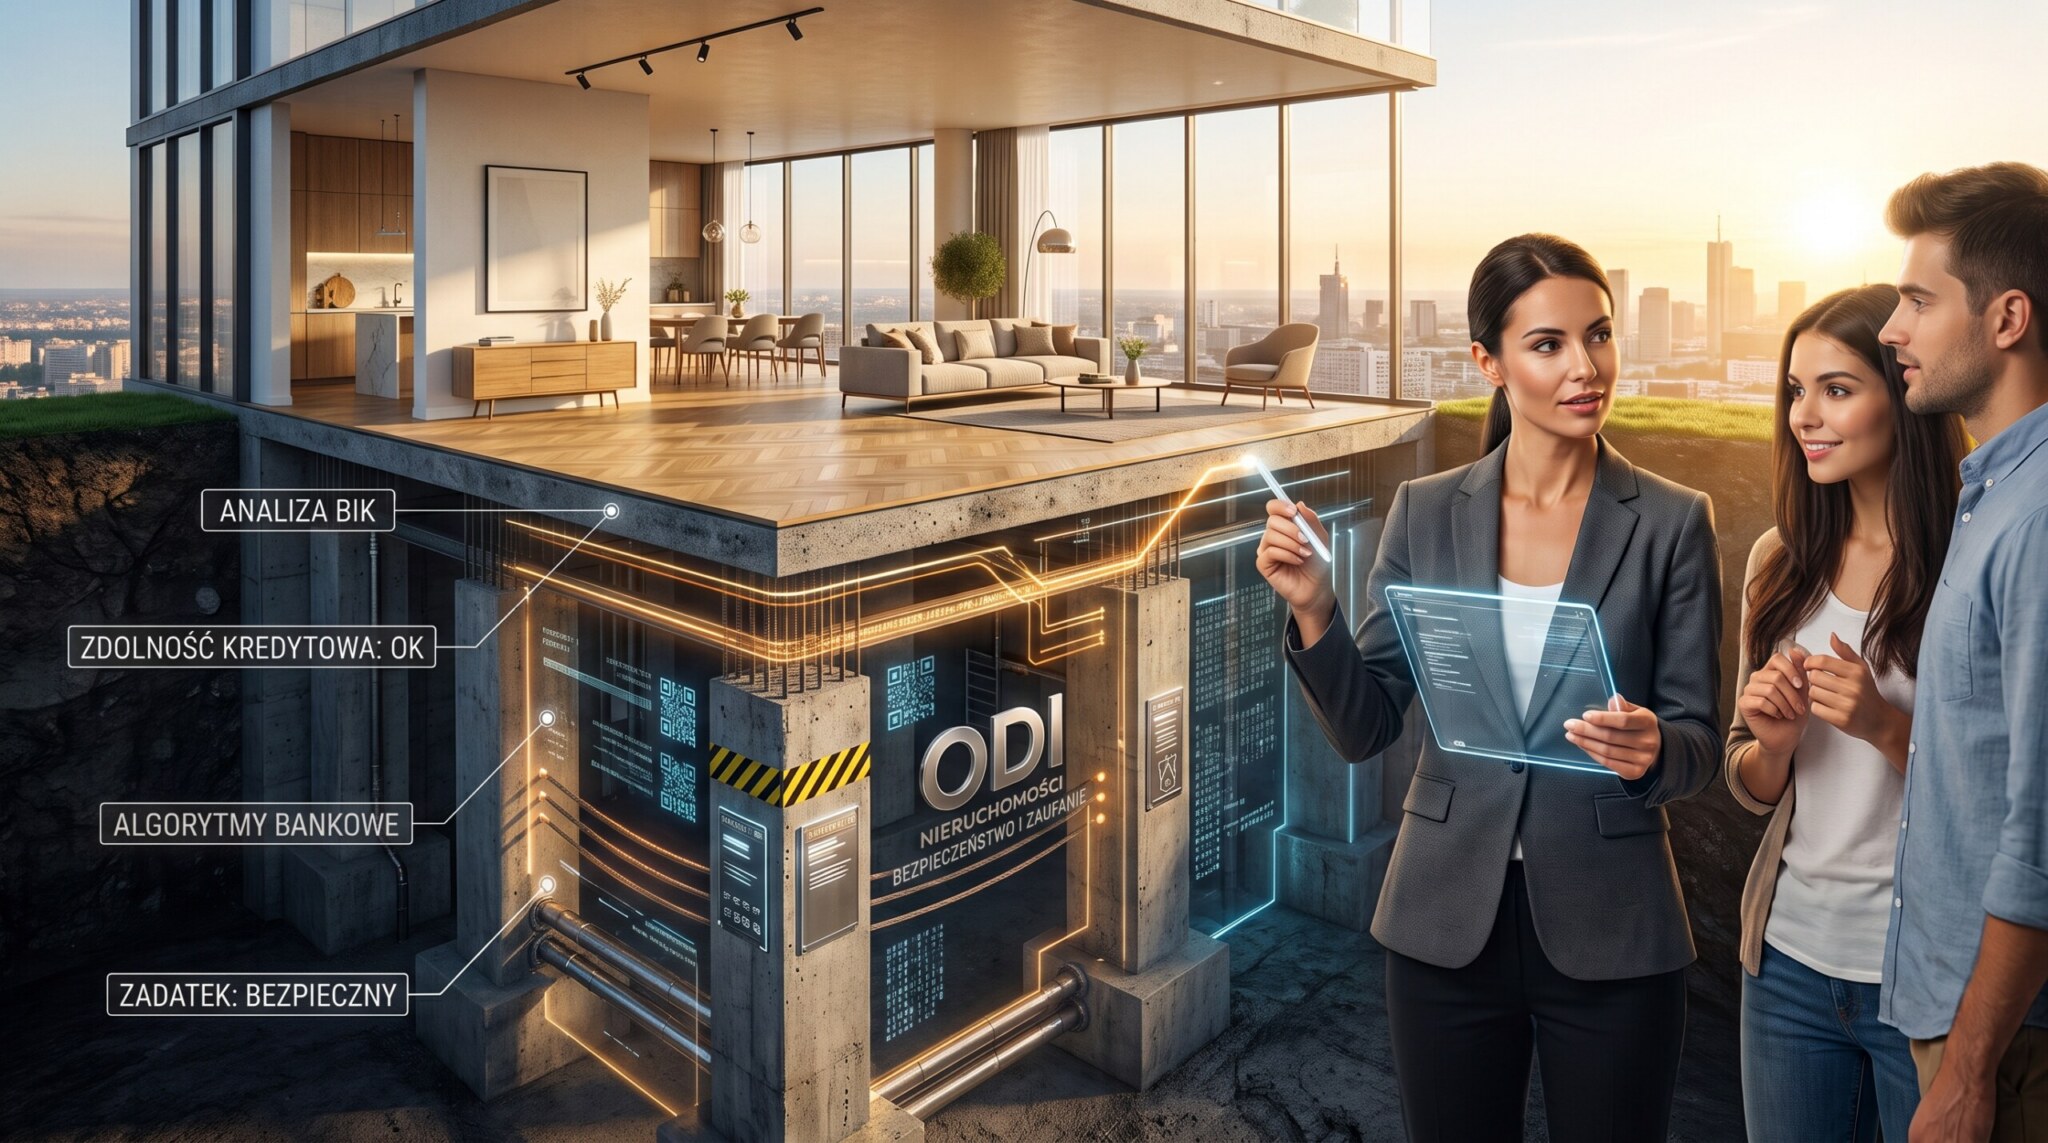
Finding the ideal property, signing a preliminary agreement, and paying earnest money is an exciting moment for every buyer. When a negative decision suddenly arrives from the bank, a justified fear of losing one's life savings appears. At ODI Real Estate, we do not treat a refusal as a final verdict. Rather, we perceive it as a specific diagnostic signal, because every financial institution calculates creditworthiness according to different algorithms.
Most common reasons for credit refusal
The key to solving the problem is a quick identification of the reason why the bank rejected the application. The most common obstacles include errors or arrears in BIK, an unfavorable income algorithm, and an undervalued property valuation by an appraiser. A forgotten installment for household appliances from four years ago or an unclosed overdraft on the account can effectively block the process of applying for financing. In such situations, we thoroughly verify the full BIK report and carry out an effective entry-clearing procedure.
- Errors or arrears in BIK blocking the credit application
- Unfavorable income algorithm for lump sum taxation or B2B contracts
- Property valuation below the purchase price ruining the LTV ratio
Differences in bank policies and income issues
Running a business on a lump sum tax or working on a B2B contract can be a challenge in some institutions. Bank A may reject the application due to lump sum costs, while Bank B will easily include net income with full acceptance of a given industry. Equally important is the property valuation itself. An appraisal report that is too low destroys the LTV ratio, which is why we provide appraisers with hard transaction data from the local market that effectively defend the real value of the property.
Transaction security at ODI Real Estate
Acting with respect for the interests of our clients, we recommend specific security steps. Before you sign a preliminary agreement, we check your creditworthiness in several independent institutions. What is more, we include a safe earnest money clause in the agreement, which guarantees the recovery of paid funds down to the last penny if the financing ultimately does not come to fruition. Feel free to contact our advisors. Check your real possibilities at odi.propertyi.pl and go through the property purchase process in a fully controlled and safe manner.
Read next
How interior depersonalization helps in the sale of a property?
Depersonalization of space is one of the most important steps when selling a property. It allows the buyer to see their own home in the apartment, which makes …
Read more →
How to safely buy a building plot
A charming location near a forest can lull your vigilance. Before you sign the preliminary agreement, check key formal and technical issues that will determine…
Read more →
Hidden costs of property purchase - how to plan your budget
The price of the property is only the beginning of expenses. Check which transaction-related fees you should keep in mind to avoid financial surprises.
Read more →