

News
Mortgage loan refusal - what to do next?
-
 Konrad Puc
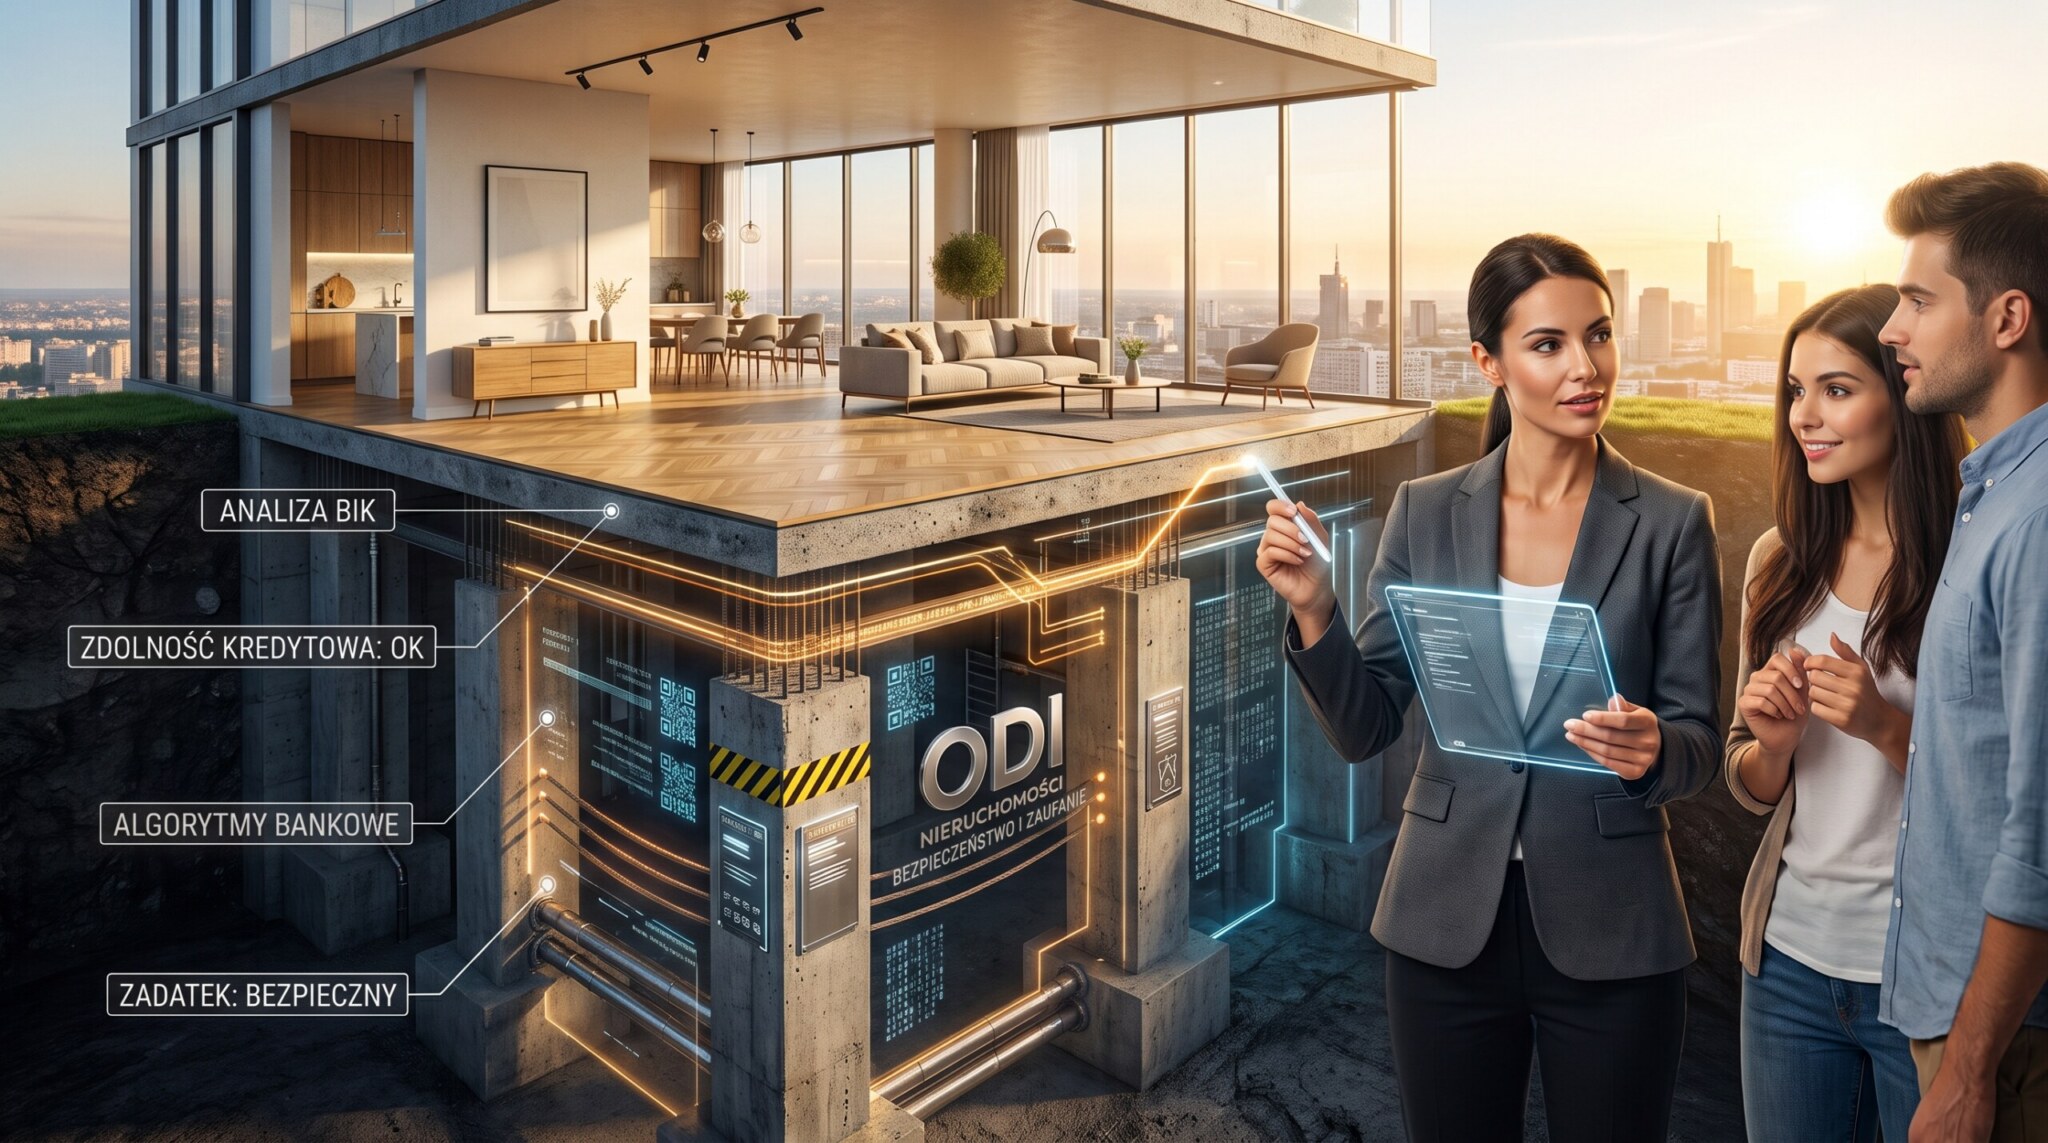
Finding the ideal property, signing a preliminary agreement, and paying the earnest money are an emotional moment for every buyer. When a negative decision suddenly arrives from the bank, a justified fear of losing one's life savings appears. At ODI Real Estate, we do not treat a rejection as a final verdict. We rather perceive it as a specific diagnostic signal, because each financial institution calculates creditworthiness according to different algorithms.
Most common reasons for credit rejection
The key to solving the problem is a quick identification of the reason why the bank rejected the application. The most common obstacles include errors or arrears in the Credit Information Bureau (BIK), an unfavorable income algorithm, and an undervalued property valuation by an appraiser. A forgotten installment for household appliances from four years ago or an unclosed overdraft on an account can effectively block the financing application process. In such situations, we thoroughly verify the full BIK report and carry out an effective procedure of clearing entries.- Errors or arrears in BIK blocking the credit application
- Unfavorable income algorithm for flat rate or B2B contracts
- Property valuation below the purchase price spoiling the LTV ratio
Differences in bank policies and income issues
Running a business on a flat rate or working on a B2B contract can be a challenge in some institutions. Bank A may reject the application due to flat rate costs, while Bank B will easily include net income with full acceptance of a given industry. Equally important is the property valuation itself. Too low of an appraisal report destroys the LTV ratio, which is why we provide appraisers with hard transaction data from the local market that effectively defend the real value of the property.Transaction security at ODI Real Estate
Acting with respect for the interests of our clients, we recommend specific safeguarding steps. Before you sign a preliminary agreement, we check your creditworthiness in several independent institutions. What is more, we include a secure earnest money clause in the agreement, which guarantees the recovery of paid funds down to the last penny if the financing ultimately does not materialize. We invite you to contact our advisors. Check your real capabilities at odi.propertyi.pl and go through the property purchase process in a fully controlled and secure manner.Read next
News
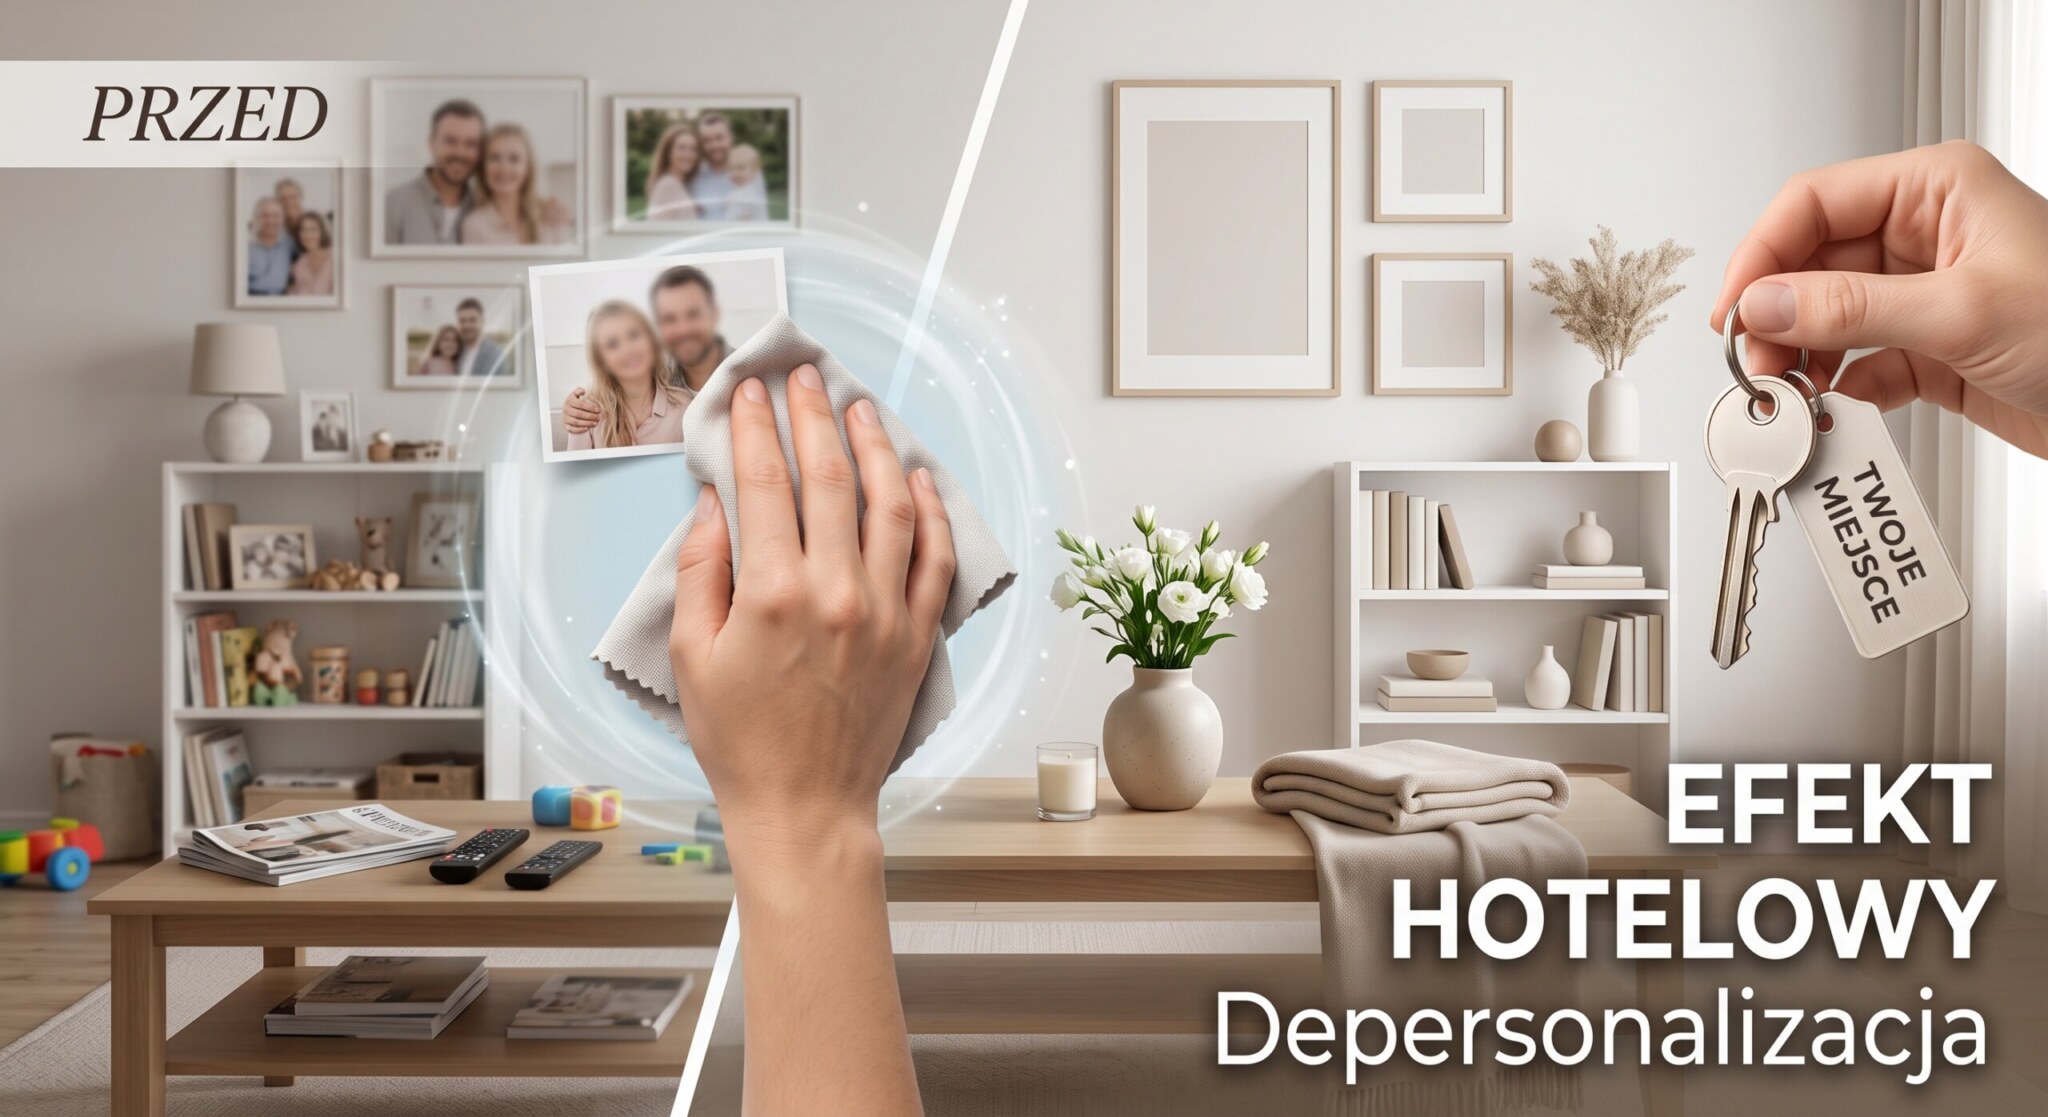
How does interior depersonalization help in selling a property?
-
Konrad Puc
Depersonalizing space is one of the most important steps when selling a property. It allows the buyer to see their own home in the apartment, which makes it ea…
Read more →
News
How to safely buy a building plot
-
 mgr Wioletta Czech
A charming location near a forest can lull your vigilance. Before you sign a preliminary agreement, check key formal and technical issues that will determine t…
Read more →
News
Hidden costs of purchasing a property - how to plan your budget
-
mgr Wioletta Czech
The price of the property is only the beginning of expenses. Check which transaction-related fees are worth remembering to avoid financial surprises.
Read more →